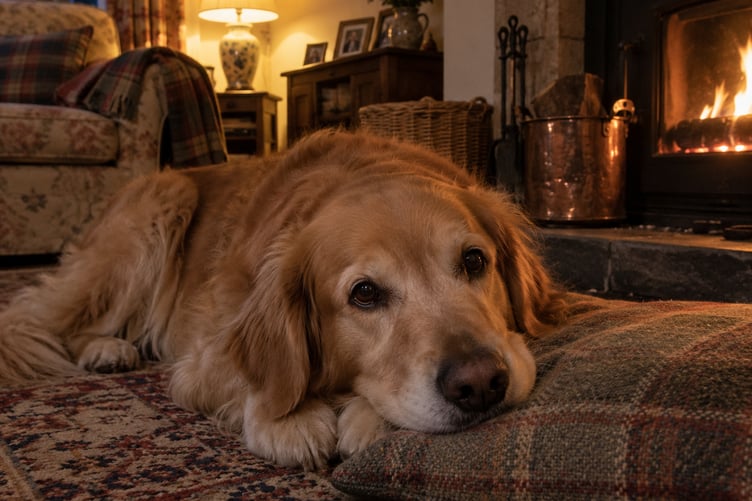
Rosie was 18 months old when she started limping on a front leg. She's a Rottweiler, and her owner assumed she'd overdone it at the park. A few weeks, several X-rays and a scan later, the diagnosis was elbow dysplasia.
Larger breeds are prone to it. According to ABI figures, elbow dysplasia is the most common cause of front-leg lameness in young, large and giant breed dogs, and treatment can cost over £50,000, though bills like that sit at the most complex end. Even a pet eating something it shouldn't costs around £4,000 to treat.
Rosie was on a maximum-benefit policy with £5,000 for each condition. It seemed plenty when she was a puppy.
Four ways a limit can work
Every policy has a ceiling on what it will pay, and how that ceiling behaves depends on the type:
- Time-limited: pays for each condition for a set period, often 12 months, usually counted from when your vet first recommended tests or treatment.
- Maximum-benefit: pays a fixed sum for each condition, and once it's used, that condition isn't covered again.
- Annual per-condition limit: a set amount for each condition in each policy year.
- Lifetime: the limit resets when the policy renews, as long as the insurer keeps offering renewal, so an ongoing condition gets a fresh amount each year.
Whichever type you have, the costs for a condition usually come out of the same limit: X-rays, a referral, surgery, painkillers and physiotherapy. Some policies also have separate, smaller limits for things like physiotherapy.
The day it's reached
The insurer pays up to the limit and stops. From that point, the bills are yours, even if treatment is halfway through.
For Rosie, the tests and the referral used a large part of her £5,000, and surgery on one elbow took the rest. Because her policy was maximum-benefit, that money wasn't coming back at renewal. The physiotherapy that followed fell to her owner.
Elbow dysplasia often affects both front legs, which raises a second question. The Financial Ombudsman lists bilateral conditions among the reasons insurers give for declining claims. Some insurers treat a problem on the second side as pre-existing, or say the time limit started when it was first seen on the other side. Search your policy wording for "bilateral" before you need it.
A limit that runs out every year
Limits don't only run out on big operations. Take Otis, a twelve-year-old cat with kidney disease on a lifetime policy with a modest annual limit. Regular blood tests, rechecks and medication draw on that limit month by month, and in a year with a flare-up it can be used before renewal. Until then, the rest of that year's kidney care is paid by his owner. Depending on the policy, another illness in the same year may also share the limit.
For older pets on long-term treatment, the size of the annual limit matters as much as the type of policy.
If it has already happened
Ask the insurer exactly what has been paid and against which condition. Check that separate problems haven't been counted together, because a second condition may have its own limit.
Then go through what's left to do with your vet. Ask which parts of the plan are most urgent, which could wait, and what each would cost. Treatment in stages is sometimes possible, but pain relief shouldn't wait, and ask whether delaying surgery would affect the outcome.
If you think the limit or other deductions have been applied unfairly, complain to the insurer first. If you're not happy with its answer, you can take it to the Financial Ombudsman, which lists unfairly applied limits among the complaints it looks at.
Cancelling and starting again with a new insurer won't bring fresh cover for the same problem. It would almost certainly be treated as pre-existing.
Choosing a limit that holds
Think about illness that could run for years, not just a single operation. Ask your vet what a referral and surgery for a common condition in your breed would cost, and set that against the limit on the quote.
Then look at how the limit behaves, not only how big it is. A policy whose limit resets each year handles a condition like Otis's differently from one that pays a fixed sum and stops, as Rosie's did. A higher limit costs more each month, so weigh that against what you could pay yourself if the cover ran out.
Rosie is doing well, with physiotherapy and weight control keeping her comfortable. When her owner asked about a higher limit, the insurer confirmed it would apply to new conditions only, so her elbows stay on the old terms.
Comments
We've recently changed our login process. If you have an account for commenting, you will need to re-register on the login window.
This article has no comments yet. Be the first to leave a comment.